

Común: Your money, your way

- 2.75K Reviews
- 4.8
- Downloads
- 500,000+
Our take on Común: Your money, your way from Appgk
I tried Común as a finance app for the everyday moments when moving money needs to feel simpler than visiting a bank or juggling several services. Its central idea is easy to understand: you can pay people, send money to Latin America, and use a Visa debit card from the same product. That combination gives it a clear identity, especially for people whose financial lives cross borders.
My first impression was that Común is less about complicated financial planning and more about making routine payments and transfers accessible from a phone. That focus matters. A person who regularly supports relatives abroad, pays friends back, or wants a debit card alongside transfer tools may find more value here than in a traditional banking app that treats international payments as an occasional extra.
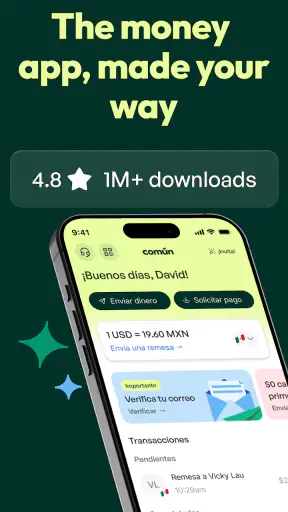
Común is free to download and is rated for Everyone, so its presentation is approachable rather than aimed at professional investors or advanced banking users. The developer is Comun, and the app has built a sizeable audience: it has passed half a million installs, with an average rating of 4.8 from roughly 22 thousand ratings. Those figures suggest that the basic proposition is resonating, although a high store rating should never replace checking whether the service fits your particular transfer needs.
How Común feels in its current form
The current version is 2.29.0, and that number gives the impression of a product that has moved beyond an early experiment. In use, I see Común as a focused financial companion rather than a complete replacement for every banking product. The useful center is the relationship between sending money, receiving money, and spending through the Visa debit card.
Best Parts of Común: Your money, your way
Things to Keep in Mind About Común: Your money, your way
That is important because these activities are connected in real life. Imagine getting paid, setting aside money for a family member in Latin America, paying a friend back for groceries, and using a card for the rest of your weekly spending. With Común, the appeal is having those actions associated with one account instead of remembering which service handles each one.
The store summary describes the product in a compact way, but the practical benefit is broader than a single transfer button. I would consider it most suitable for people who want a straightforward way to move money and then access it through a card. It is also potentially useful for households where one person sends support across borders while still needing ordinary payment functionality at home.
News and Features Related to Común: Your money, your way

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
That convenience has a trade-off: a combined service deserves more careful setup than an app used only to send a one-time payment. Before relying on it for important expenses, I would make sure my identity details, recipient information, and card arrangements were all ready. A smooth first transfer is helpful, but dependable financial routines are built by testing the complete path from funding to sending to spending.
Where the app fits better than a traditional bank
Traditional banking apps often do everyday payments well, but international transfers may feel like a separate process, with unfamiliar terminology or extra steps. Común’s appeal is that cross-border sending is not an afterthought in its identity. If Latin America is part of your regular financial routine, that emphasis can make the app easier to understand than a general-purpose account that happens to offer international transfers.
Don't want to read the full review?
It can also be more convenient than maintaining one app for a debit card and another for transfers. I would not assume that combining services automatically makes every transaction cheaper or faster; those details can depend on the route, the recipient, and the transaction conditions shown to you. The real advantage is organizational: fewer places to check and a clearer mental model for money that needs to move between people and countries.
Compared with a money-transfer specialist, Común may appeal more if you also want a Visa debit card rather than only a remittance tool. A specialist can be the better choice when your sole priority is comparing a particular corridor or sending a large, occasional payment. Común makes more sense when sending and spending belong to the same weekly routine.
Screenshots
What has changed by the current release
The available release information identifies version 2.29.0 as the current build. That is useful context because it shows that I am assessing an active product rather than an abandoned listing. Still, a version number alone does not prove that every part of the experience has been transformed. I would separate what is visible now from what I hope future updates improve.
From a user’s perspective, the important sign of product evolution is not simply a newer number. It is whether the app makes the core journey clearer: opening the account, understanding available money, choosing a recipient, reviewing a transfer, and knowing how the debit card fits into the same balance. Those are the areas where small interface improvements can prevent expensive misunderstandings.
For existing users, an updated release can be valuable even when the main features look familiar. Finance apps need to keep their flows understandable as they expand, because an extra option placed in the wrong part of a transfer screen can create hesitation. My advice is to read each confirmation screen carefully after an update, especially when sending to a new recipient or using the card for the first time after a change.
I would also avoid treating the current release as a promise about the roadmap. The app’s direction is clear enough to evaluate today, but expectations about future corridors, card controls, or additional banking tools should remain expectations until they are actually visible in the product. That distinction protects users from planning around features that may never arrive.
How existing users may benefit from the unified setup
If you already use Común, the strongest benefit is likely continuity. Instead of switching between a remittance service and a card account, you can think about your money in one place. That can reduce the small mistakes that happen when you copy recipient details into one app, check a balance in another, and then forget which service holds the funds you meant to spend.
A practical workflow is to separate your intentions before opening the app. Decide whether you are paying someone locally, sending support to Latin America, or preparing to spend with the Visa debit card. That simple pause helps you review the right recipient and amount instead of rushing through a familiar screen. It is a small habit, but it matters more when several kinds of transactions share one financial space.
Another useful habit is to treat recipient setup as a deliberate task rather than something to do while distracted. For a recurring family transfer, verify the person and destination before confirming the first payment, then keep your own record of the purpose and date. The app can make sending convenient, but personal organization remains important when transfers become regular.
The card adds another layer of usefulness. I would use it for ordinary spending only after confirming that the account balance and card status are easy for me to monitor. A combined transfer-and-card app can simplify access to money, but it also means a mistake in how you understand the available balance can affect both sending and spending plans.
Where the experience still needs care
Común is not automatically the right choice for every financial situation. Someone who needs a full traditional bank relationship, extensive account products, or advanced budgeting and investing tools may find the app too focused. Its strength is the connection between payments, international transfers, and a debit card, not an attempt to cover every possible financial job.
I would also be cautious if your needs are occasional and highly specialized. If you send money only once in a while, comparing a dedicated transfer service for that exact destination may be more sensible than adopting a broader account. Likewise, if you already have a debit card and a bank setup that you enjoy, switching just for the convenience of consolidation may not justify the learning curve.
Cross-border money movement also requires patience with details. Exchange rates, transfer timing, recipient eligibility, verification steps, and transaction limits can all affect the practical result, and these are the kinds of things I would check inside the app before confirming an important payment. I would never judge a financial service only by how quickly its home screen opens.
There is also a human limitation that no interface can remove: the sender and recipient must use accurate information. A polished flow cannot rescue a payment sent to the wrong person. For a first transfer, I would send a modest amount, confirm that the recipient receives it correctly, and only then make the process part of a larger recurring routine.
A realistic week with Común
Consider a user who receives income into a main account, sends regular support to a relative in Latin America, and wants a separate way to pay for small daily purchases. That person could use Común as the bridge between those needs: move the intended amount into the account, review the international recipient, send the payment, and use the Visa debit card for spending that remains.
The advantage is not that every step becomes effortless. The advantage is that the user has one place to revisit when checking what happened. If a transfer is important, I would still save the confirmation details and keep a simple note outside the app. That gives me an independent reference if I later need to remember the amount, recipient, or reason for the payment.
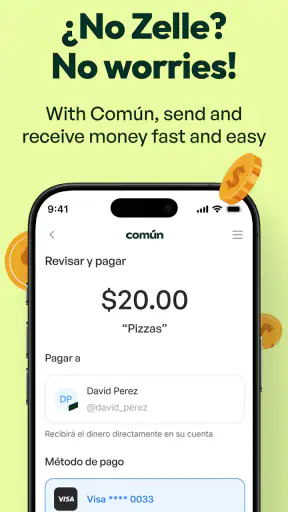
For shared expenses, the same setup can be convenient. A friend can be paid back without turning a bank transfer into a lengthy project, while the card handles purchases that would otherwise require another account. But I would avoid mixing personal spending and family support without a basic mental budget. Convenience can make money movement feel invisible, and invisible spending is difficult to control.
This is where Común feels most convincing to me: not as a magic solution, but as a practical home for connected money habits. It can shorten the distance between “I need to send this” and “I need access to the rest,” provided the user is willing to review the details instead of tapping through automatically.
Questions I would settle before relying on it
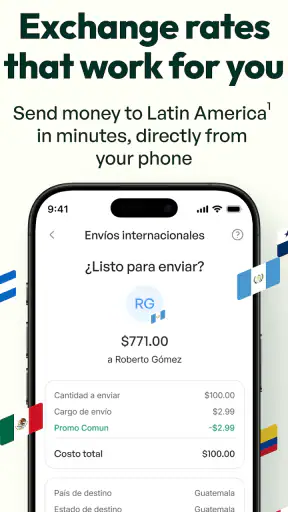
The first question is whether it works for your particular destination and recipient. The app is explicitly built around sending money to Latin America, but “Latin America” covers many different locations and circumstances. I would check the recipient’s country and the exact transfer route in the app before promising a payment to someone else.
The second question is whether the Visa debit card matches your spending habits. If you want one card connected to the same financial setup used for transfers, it is a natural fit. If you need several specialized cards, extensive controls, or a long-established bank ecosystem, a conventional bank may serve you better.
The third question is how much you value consolidation. I like the idea of reducing app switching, but consolidation is useful only when the combined experience remains understandable. During the first few uses, I would pay attention to how balances, transfers, and card spending are presented. If I cannot quickly tell what money is available for which purpose, I would keep my existing arrangement until that becomes clear.
The fourth question is whether you need advanced financial management. Común’s identity is centered on payments, transfers, and spending access. For investing, detailed household budgeting, business accounting, or complex credit needs, I would look for tools designed specifically for those jobs rather than expecting this app to become a complete financial command center.
What I would watch in future use
As the product develops, I would watch how clearly it explains the cost and timing of each international transfer before confirmation. That information is more important than a decorative redesign because it directly affects whether a recipient gets the expected amount and when the money becomes available.
I would also watch the relationship between the card and the transfer balance. The best experience would make it obvious how spending changes what can be sent, and how incoming money affects card use. Clear separation between pending activity and usable funds would be especially valuable for people who rely on Común for recurring family support.
Finally, I would look for continued attention to reliability around the moments that matter most: adding a recipient, confirming a cross-border payment, and resolving a problem without confusion. A finance app earns trust through those details. The current version gives Común a credible foundation, but long-term confidence comes from consistent handling of real-world exceptions, not simply from having a clean central concept.
My recommendation
I recommend Común to people who regularly pay others, send money to Latin America, and want a Visa debit card tied to the same financial experience. The free price makes it easy to explore, and its focus is more distinctive than that of a generic wallet. The strong user response, including an average rating of 4.8 and more than two thousand written reviews, supports taking a serious look at it rather than dismissing it as a niche experiment.
My recommendation is more cautious for users who need a full-service bank, highly specialized transfer comparisons, or advanced money management. In those cases, the usual alternative may be better, even if it means keeping separate tools. Común’s value comes from bringing related tasks together, not from replacing every financial service.
My honest takeaway is that Común works best when international support and everyday spending are part of the same routine. I would start with a small, low-pressure transaction, learn how the transfer and card sides connect, and then decide whether it deserves a larger role in my finances. For the right user, that measured approach can turn a promising finance app into a genuinely convenient daily tool.
Común: Your money, your way FAQ
What is Común: Your money, your way?
Común: Your money, your way is a personal finance app designed to help users organize, monitor, and manage their money from one place. Depending on the services available in your region, it may provide tools for viewing balances, tracking transactions, planning spending, and handling everyday financial activity. Before downloading, check whether its supported features and eligibility requirements apply to your country.
Is Común safe to use for managing personal finances?
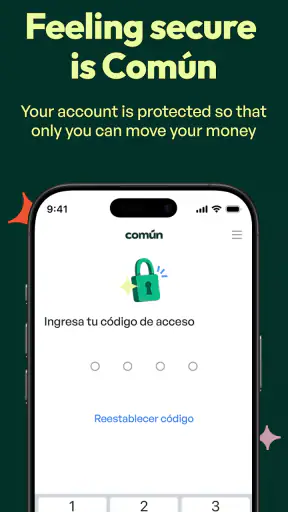
Financial applications require access to sensitive information, so security should be a priority before creating an account. Común may use account authentication, encryption, and other protective measures, but users should still review its privacy policy and permissions carefully. Download the app only from an official store, use a strong unique password, enable available security options, and never share verification codes with anyone.
Does Común charge fees or require a subscription?
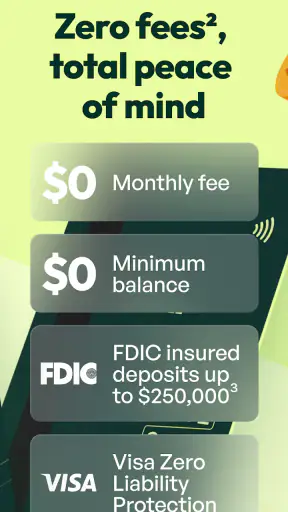
The cost of using Común can depend on the account type, financial products selected, transactions performed, and the country where you live. Some features may be free, while others could involve service, transfer, withdrawal, exchange, or subscription fees. Review the current pricing information inside the app or on the official website before sending money or activating any optional service.
Can I use Común if I live outside its supported region?
Común may not be available to every user worldwide. Registration can depend on your country of residence, age, identity verification documents, phone number, and access to compatible financial services. Even if the application can be downloaded in your location, certain functions may be restricted. Confirm regional availability and eligibility requirements before starting the sign-up process.
What should I do if I have a problem with my account or transaction?
If you experience a failed transaction, unexpected charge, login issue, or verification problem, first check the app’s help center and transaction details. Contact Común through its official support channels rather than relying on unofficial social media accounts or third parties. Keep relevant dates, receipts, and reference numbers available, and avoid sharing your password or security codes during support conversations.











